
Car Insurance Companies and Agents in Los Angeles: Who to Compare
Compare top car insurance companies and agents in Los Angeles. Learn who to trust, how to save, and where to find the best coverage and quotes.
Navigating Auto Coverage in the City of Angels
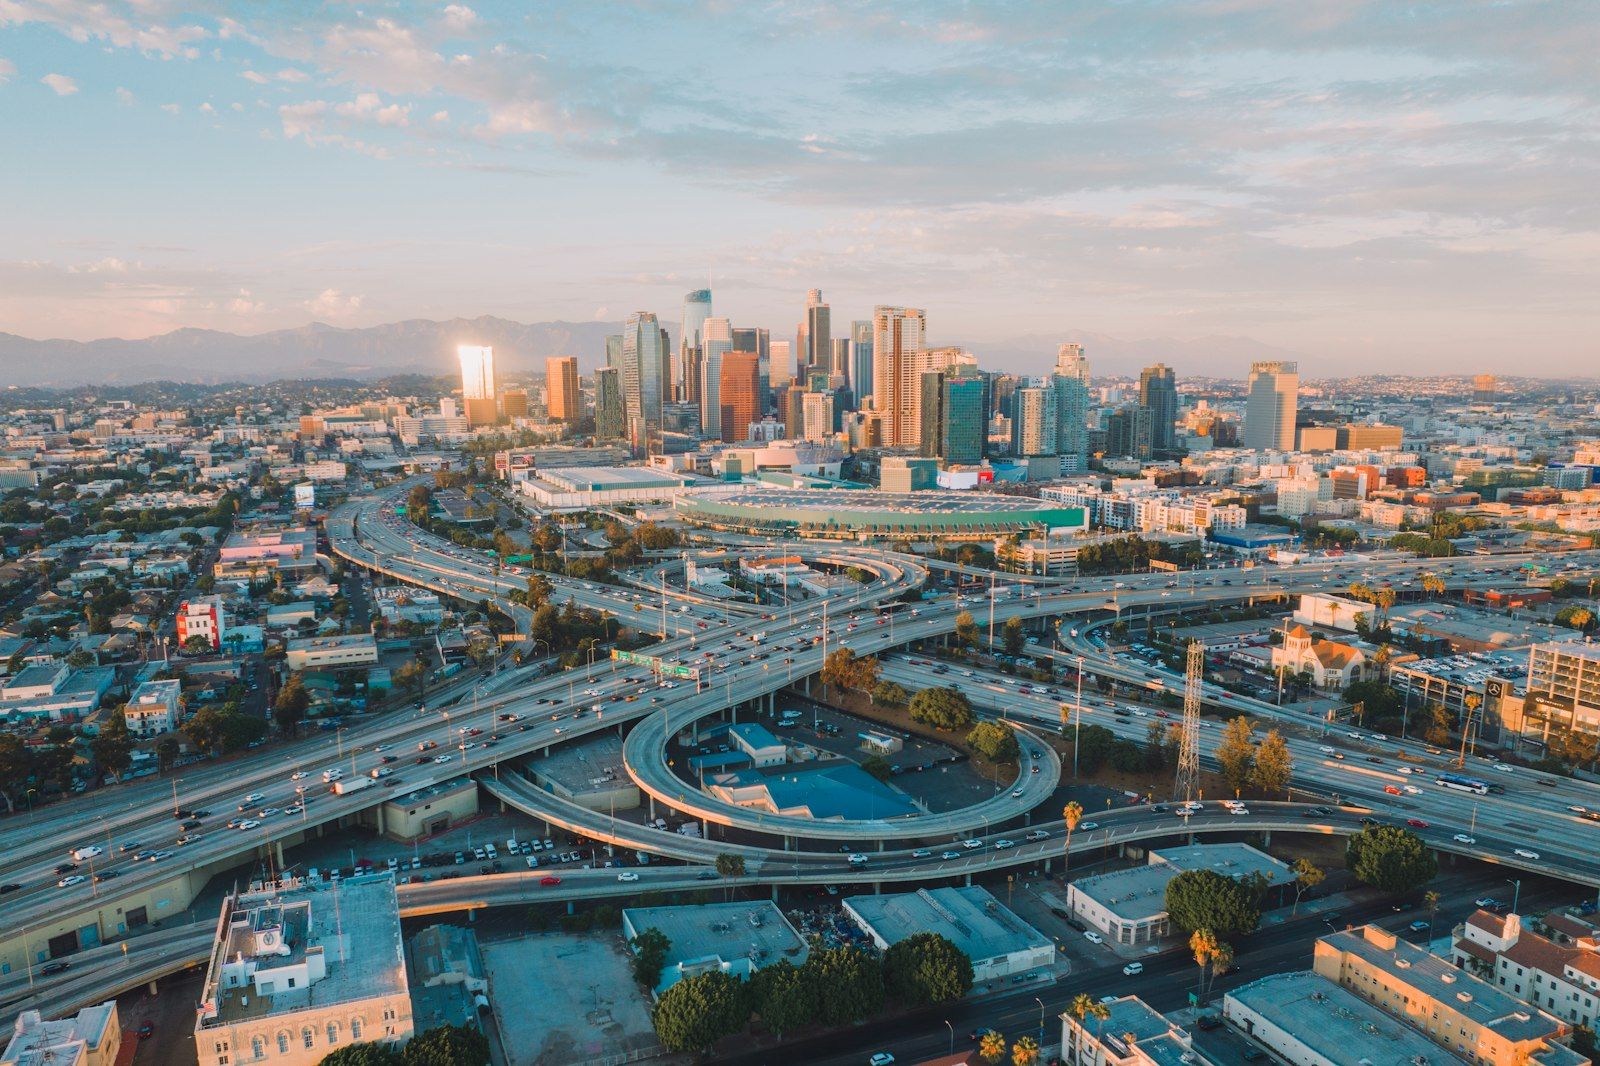
Driving in Los Angeles is an experience unlike any other in the country. Between navigating bumper to bumper congestion along the 405, merging across five lanes on the 10, and dodging debris along surface corridors like Wilshire Boulevard, your vehicle is exposed to daily hazards that drivers in quieter regions rarely encounter. In our years working with California drivers, we have seen firsthand how easily an unexpected commute mishap can turn into a serious financial crisis if your policy is not structured correctly.
When your monthly premium bill arrives or you purchase a new vehicle, the natural reaction is often to pick up a smartphone and search for LA car insurance near me. You are immediately flooded with dozens of options: massive national advertisers promising instant online savings, regional insurance carriers, and neighborhood storefronts. Yet selecting the right policy involves far more than picking the lowest monthly payment on a comparison app.
Finding the right coverage requires understanding the different types of providers available across Southern California, from national direct carriers to established local carriers and independent insurance brokers. Taking a careful, detail oriented approach to evaluating personal auto insurance ensures that your hard earned assets, your savings, and your daily commute are truly protected when you need it most.
How Los Angeles Car Insurance Companies Price Your Policy
To effectively evaluate Los Angeles car insurance companies, you first need to understand the unique regulatory and geographic environment that shapes auto insurance rates across Southern California.
California regulates auto insurance rates under Proposition 103, an initiative passed by voters that places strict limits on the factors insurers can use to determine premiums. In many other states, carriers rely heavily on credit scores, gender, or homeownership status to determine rates. In California, that is illegal. Under the oversight of the California Department of Insurance, insurers must base their rates primarily on three mandatory factors:
- The insured driver's safety record, including moving violations and at-fault accidents over the prior 36 months.
- The average number of miles driven annually.
- The number of years of driving experience the policyholder has accumulated.
Insurers can also factor in secondary elements such as vehicle type, garaging location (determined by ZIP code), marital status, and whether the vehicle is used for business or pleasure.
Because ZIP codes play a notable role, car insurance companies in Los Angeles, California often charge rates that run 25% to 35% higher than the California state average. Los Angeles County features an unusually high density of vehicles per square mile, higher rates of vehicle property theft and vandalism, and some of the highest average medical and collision repair costs in the United States.
A critical legislative change recently altered this landscape. Under Senate Bill 1107, California modernized its mandatory minimum financial responsibility limits for the first time in more than five decades. For policies issued or renewed starting January 1, 2025, the minimum liability limits doubled from the old 15/30/5 baseline up to:
- $30,000 for bodily injury or death per person in an accident.
- $60,000 for bodily injury or death for two or more persons in an accident.
- $15,000 for property damage per accident.
According to the California DMV, every registered vehicle must maintain these minimum liability limits to remain legally compliant. While this change was overdue, a $15,000 property damage limit can be exhausted in seconds during a multi-car chain reaction on the freeway, especially considering the average price of modern vehicles and electric cars traversing Los Angeles. This reality is why comparing auto insurance companies in Los Angeles with an eye for adequate liability limits is so vital.
Three Paths to Buying Coverage: Direct, Captive, and Independent Brokers
When you start comparing providers, you will quickly notice that insurance is sold through three distinct business models. Understanding how these channels function helps you determine which path provides the best balance of price, guidance, and claim advocacy.
1. Direct-to-Consumer Insurance Carriers
Direct carriers allow you to buy policies straight from an online portal, mobile app, or national call center without meeting an agent.
- Advantages: Convenience is the primary draw. You can request a quote at midnight, adjust coverage sliders on a screen, and obtain an electronic insurance binder immediately.
- Disadvantages: You are entirely on your own when determining policy limits. If you choose coverage that leaves your personal assets vulnerable, or if you accidentally misstate your annual commute mileage, you might discover severe coverage gaps only after filing a claim. Furthermore, customer service is typically handled through rotating call center queues where you rarely speak to the same representative twice.
2. Captive Insurance Agents
Captive agents represent a single insurance company, such as State Farm, Farmers, or the Automobile Club of Southern California (AAA).
- Advantages: You gain a dedicated local agent who understands your neighborhood and can review your coverage options face to face or over the phone.
- Disadvantages: A captive agent can only sell products offered by their parent corporation. If that single carrier experiences underwriting restrictions or announces a double-digit rate hike across California, the captive agent cannot shop around for you. You either accept the rate increase or begin the tedious process of shopping from scratch.
3. Independent Insurance Brokers
Independent insurance agencies and brokers work for you rather than for an individual insurance company. Independent agencies partner with multiple vetted carriers, including regional stalwarts, national providers, and specialized underwriting markets.
- Advantages: An independent broker performs comprehensive market comparisons on your behalf. They examine your vehicle, driving history, commute habits, and asset protection needs, and then gather quotes across multiple competing carriers. If one carrier raises rates at renewal, an independent broker can seamlessly transition your policy to another carrier without you having to re-enter all your information.
- Disadvantages: Independent brokers place a premium on thorough underwriting. The quoting process often requires a bit more detailed verification upfront to ensure you receive accurate, dependable pricing that will not change during underwriting review.
For drivers looking for in-depth insights on navigating the broader market landscape, exploring insurance in Los Angeles provides valuable context on how local distribution shapes your customer experience.
Evaluating Major Carriers: From National Giants to Mercury Insurance in Los Angeles
When reviewing car insurance companies across Los Angeles, drivers encounter a mix of nationwide brands and strong regional specialists. Knowing how each carrier positions itself helps you pinpoint where you fit best as an applicant.
National Brands: Scale and Digital Tools
Companies such as Progressive, Geico, Allstate, and Travelers represent the largest slice of the national auto insurance market. These companies invest heavily in digital platforms, offering user-friendly smartphone apps that make downloading ID cards and filing initial damage photos fast and easy.
National carriers often excel when underwriting drivers with clean records who want quick policy management tools. However, national automated rating algorithms can sometimes penalize urban Los Angeles drivers heavily for minor infractions or high-mileage commutes. In an evolving market, national carriers have also been known to adjust their California underwriting guidelines suddenly, tightening eligibility rules or placing temporary waiting periods on new policy issuance. For a deeper breakdown of the forces driving these shifts, you can read our analysis on shifts across the insurance industry.
Mercury Insurance: The California Heritage Carrier
You cannot discuss auto coverage in Southern California without mentioning Mercury Insurance. Founded right here in Los Angeles in 1961 by George Joseph, Mercury Insurance was created specifically to provide competitive, value driven automobile coverage for California drivers. Today, Mercury remains one of the largest private passenger automobile insurers in the state.
When evaluating Mercury Insurance in Los Angeles, policyholders often find several distinct advantages:
- Competitive Local Pricing: Because of its extensive historical claims data in Los Angeles County, Mercury car insurance in Los Angeles frequently delivers some of the most competitive pricing for drivers who maintain clean to moderate driving records.
- Independent Broker Network: Unlike direct carriers, Mercury distributes its policies almost exclusively through licensed independent agents and brokers. This model pairs competitive carrier pricing with personalized, local broker support.
- Bundling Opportunities: Mercury provides significant multi-policy discounts when you pair auto coverage with homeowners, condominium, or renters insurance. For property owners in Southern California, this multi-line approach often provides substantial cumulative savings.
- Practical Coverage Endorsements: Mercury offers targeted add-ons such as mechanical protection, roadside assistance, and rideshare coverage tailored for drivers operating on platforms like Uber or Lyft throughout the greater Los Angeles metro area.
However, Mercury is also known for maintaining strict underwriting and claims verification standards. They examine application details carefully, meaning that precise reporting of garaging addresses, primary drivers, and commute mileage is essential when binding coverage through this carrier.
Specialized and Non-Standard Insurers
If your driving record includes recent at-fault collisions, multiple speeding tickets, or a suspended license requiring an SR-22 filing, major carriers may decline coverage or offer prohibitively expensive rates. Non-standard carriers such as Kemper Auto, National General, or the California Automobile Assigned Risk Plan (CAARP) specialize in higher-risk profiles. Independent brokers routinely work with these non-standard programs to keep drivers legally insured while they rebuild their clean driving record.
To learn more about how different providers compare for various driver profiles, check out our guide to the best car insurance options in Los Angeles.
The Real Value of Car Insurance Agents in Los Angeles, CA
With so many direct websites and automated quote aggregators available, why do hundreds of thousands of California drivers still choose to work with local car insurance agents in Los Angeles, CA?
The answer comes down to local expertise, personalized advocacy, and attention to detail.
Navigating Los Angeles Commute Realities
An algorithm operating on a remote server in another state does not understand the difference between parking your car on the street in Koreatown versus garaging it behind a gate in Sherman Oaks. It does not factor in the unique exposure of driving the canyon routes between the San Fernando Valley and West LA during winter rains.
A local agent or broker understands the local environment. When setting up your policy, a seasoned professional will ask specific questions about your daily driving patterns:
- Do you commute on freeways, or do you primarily take public transit and use your vehicle on weekends?
- Do you use your vehicle for business meetings, deliveries, or ridesharing?
- Where is your vehicle stored overnight?
Accurately answering these questions ensures you do not overpay for mileage you do not drive, while preventing insurance carriers from challenging a claim based on inaccurate policy disclosures.
Navigating Uninsured and Underinsured Motorist Risks
One of the most compelling reasons to consult an experienced agent in Los Angeles involves uninsured motorist coverage. Despite state mandates, California regularly ranks high for the total number of uninsured and underinsured motorists on the road.
If an uninsured driver rear-ends your car on the Santa Monica Freeway and speeds off, a basic liability policy will pay zero dollars toward your medical bills or vehicle repairs. Working with an agent ensures you carry robust Uninsured Motorist Bodily Injury (UMBI) and Uninsured Motorist Property Damage (UMPD) limits, shielding your family from the negligence of other drivers.
Claim Advocacy When It Counts
When a serious accident happens, dealing with insurance adjusters can be intimidating and stressful. Direct carriers often route your call to an entry level claims handler who manages hundreds of files at once.
When you work with a dedicated local agency, you have a direct advocate in your corner. Your agent can guide you through the process, explain your deductible responsibilities, help coordinate with approved repair facilities, and ensure your claim is processed fairly and promptly. That human touch provides priceless peace of mind during an already difficult situation.
For a broader perspective on selecting regional representation, read our overview on auto insurance in Los Angeles.
Essential Comparison Checklist for Southern California Drivers
When comparing auto insurance quotes across companies, comparing the total premium alone can lead to serious errors. One insurer might appear $40 a month cheaper simply because it stripped out roadside assistance, raised your comprehensive deductible, or reduced your liability protection to bare state minimums.
To compare policies accurately, use this practical checklist to ensure an apples-to-apples evaluation:
- Bodily Injury Liability: Does the quote offer adequate protection? While the state minimum is $30,000 per person and $60,000 per accident, serious injuries can quickly result in hospital bills exceeding hundreds of thousands of dollars. We strongly advise drivers who own homes or maintain retirement savings to consider limits of at least $100,000/$300,000 or $250,000/$500,000, ideally backed by a personal umbrella policy.
- Property Damage Liability: With luxury SUVs and high-end electric vehicles filling every corner of Los Angeles, a $15,000 minimum limit is dangerously inadequate. Opting for $50,000 or $100,000 in property damage liability adds only a modest sum to your monthly premium while shielding your bank accounts from devastating subrogation lawsuits.
- Uninsured/Underinsured Motorist Coverage: Verify that your UM/UIM limits match your bodily injury liability limits. Never waive this essential protection in Southern California.
- Physical Damage Deductibles: Compare collision and comprehensive deductibles carefully. Selecting a $1,000 deductible instead of a $500 deductible can noticeably reduce your ongoing premium, but make sure you have that cash set aside in an emergency fund should an accident occur.
- Comprehensive Coverage Perils: Ensure your policy includes comprehensive protection for auto glass replacement, vandalism, falling branches, and vehicle theft. These risks are common across the city.
- Endorsements and Add-Ons: Check whether the quote includes rental car reimbursement, towing and roadside service, or original equipment manufacturer (OEM) replacement parts endorsements.
If you come across industry jargon while reviewing policy documents, our guide to insurance coverage definitions breaks down key terms into plain, accessible language.
How to Secure Maximum Value Without Cutting Protection
Lowering your auto insurance expense in Los Angeles does not require sacrificing critical safety nets. By working strategically with your insurance professional, you can take advantage of numerous legitimate rating discounts available across California:
- Calibrate Your Annual Mileage: Because California Proposition 103 places high weight on annual mileage, keeping your reported mileage accurate is one of the most effective ways to lower your rate. If you shifted to a remote or hybrid work schedule, notify your agent. Dropping from 15,000 miles to 8,000 miles per year can result in significant percentage savings.
- Bundle Auto with Home, Condo, or Renters Policies: Multi-policy discounts remain one of the most substantial savings tools in the insurance industry. Bundling your auto coverage with your living arrangements not only reduces rates across both policies but also consolidates your billing into a single convenient account.
- Maintain a Clean Motor Vehicle Record: Under California law, drivers who maintain a clean record free of moving violations and at-fault accidents for three consecutive years qualify for mandatory California Good Driver discounts, which provide meaningful rate reductions.
- Inquire About Professional and Alumni Affiliations: Many carriers offer specialized affinity discounts for engineers, educators, healthcare professionals, certified public accountants, attorneys, and alumni associations from major California universities.
- Install Anti-Theft Devices: Having an approved vehicle recovery system or factory installed alarm can qualify your vehicle for additional comprehensive discounts.
- Choose Electronic Billing and Paid-in-Full Options: Many carriers waive administrative processing fees or offer upfront discounts when you enroll in automated electronic payments or pay your six-month policy premium in full.
Case Studies: Real-World Lessons from the Freeway
To see the tangible value of proper comparison and agent support, consider these two real-world scenarios from our daily practice.
Case 1: The Misleading Online Slider
A professional living in Culver City decided to shop online to replace an auto policy that had renewed at an elevated rate. Using a direct insurance portal, she adjusted the coverage sliders to make the monthly payment fit her exact target budget, ultimately purchasing a policy with state minimum liability limits of $30,000/$60,000/$15,000 and dropping uninsured motorist protection.
Six months later, while driving near the intersection of Venice and La Cienega, another driver ran a red light, striking her sedan and pushing it into a luxury electric vehicle waiting in the turn lane. The at-fault driver fled the scene on foot and was never located.
Because she had dropped uninsured motorist coverage to save approximately $18 a month, she had no first-party medical reimbursement for her emergency room visit. Even worse, the luxury car owner's insurer filed a claim against her for secondary property damage exceeding $45,000, far exceeding her $15,000 policy limit. She was forced to pay out-of-pocket legal fees and draw down savings to resolve the dispute. A twenty-minute policy review with a knowledgeable broker could have prevented this entire financial ordeal.
Case 2: The Multi-Line Adjustment with Mercury
A married couple residing in Pasadena owned two vehicles and insured them through a direct national carrier for five years. When their renewal premium increased by nearly 22% due to citywide rate filings, they reached out to an independent broker for an objective second opinion.
The broker reviewed their existing declarations page and uncovered several key points. First, their commute mileage was still listed at 14,000 miles per year for both cars, even though both spouses had transitioned to working from home three days a week, lowering their real mileage to roughly 7,500 miles annually. Second, their condo insurance was placed with an entirely separate carrier, meaning they missed out on cross-policy discounts.
The broker ran comparative quotes across multiple regional and national carriers, identifying Mercury Insurance in Los Angeles as the strongest overall fit. By pairing their auto coverage with a revised Mercury condo policy, correcting their verified annual mileage, and applying a good driver discount, the couple secured $250,000/$500,000 liability limits, significantly higher than their previous coverage, while saving more than $850 annually across their combined insurance portfolio.
Making the Right Choice for Your Commute and Asset Protection
Driving in Los Angeles is demanding, and shopping for car insurance in this dynamic market can easily feel overwhelming. However, you do not have to navigate the fine print, the changing state laws, or fluctuating carrier rates on your own.
Whether you are evaluating national brands, exploring regional options like Mercury Insurance, or looking for an agency that handles the comparison work for you, prioritizing comprehensive protection over bare minimum compliance is always the wisest strategy. When you take the time to evaluate carrier financial strength, policy features, and professional guidance, you turn your auto insurance from an annoying monthly expense into a dependable financial shield.
Shieldly Premier Insurance Solutions
Ready to make sure you’re properly covered without overpaying? Contact Shieldly Premier Insurance Solutions for a detailed insurance review and side-by-side quotes, and we’ll walk you through your options so you can choose the right coverage with confidence.
At Shieldly Premier Insurance Solutions, our mission is helping and educating California drivers. Based in Mission Viejo and proudly serving drivers across Los Angeles and all of California, our agency takes an independent, detail oriented approach to evaluating your insurance needs. We do not believe in one-size-fits-all policies or leaving your financial security to an automated online guess.
Whether you want to compare quotes from top carriers like Mercury Insurance and national providers or simply review your existing policy limits, we are here to help. Visit our homepage to request a customized quote and let our experienced team streamline your insurance shopping experience today.